Did You Know?
We serve loans, the best way you can borrow
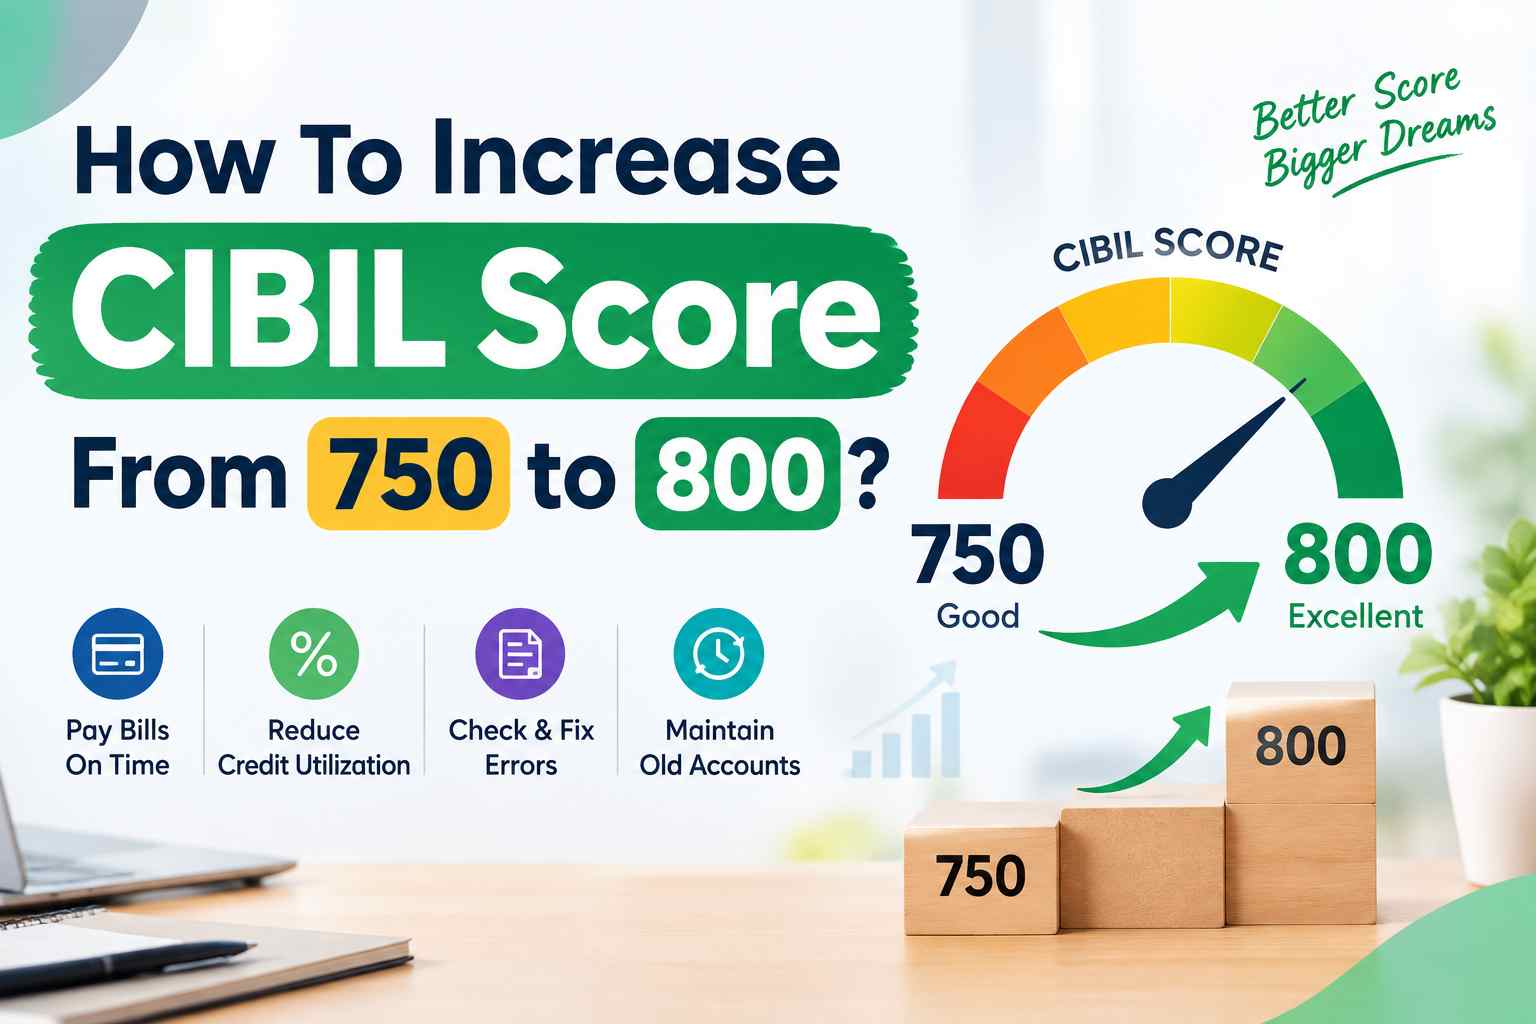

A CIBIL score of 750 is considered to be very strong. It helps you get faster loan approvals and better terms from banks and NBFCs. But a CIBIL score of 800 or above comes with its own premium benefits. At this score, a borrower is considered low risk and trustworthy and is eligible for lower interest rates, higher credit limits, higher loan amounts, pre-approved credit card offers and various other benefits of elite range.
A good score can also be helpful in your EMIs. It will help you get loans at a lower interest rate, which will decrease your EMI amount, tenure and overall interest cost. In addition to this, you also get additional credit card rewards. But the real concern is how to increase CIBIL score from 750 to 800. In this blog, we will study this in detail.
The question may arise in your mind: “I already have a CIBIL score of 750, then why should I focus on increasing it to 800?” Here are some of the major reasons for increasing CIBIL score from 750 to 800 –
An applicant with a score of 800 or above is considered low risk by the lender. They are confident in the repayment of loans from such applicants. This improves the chances of loan approval.
A strong CIBIL score can help you get loans at lower interest rates. This is because borrowers with a high credit score are considered more trustworthy, as they have a good repayment history and there is less risk of loan default.
Lenders take into consideration your repayment history while determining your loan amount. A higher credit score can get you higher limits on a credit card. It can also get you a loan of a higher amount. However, limits are not determined by the credit score itself. Income, existing liabilities, and the lender’s internal policies also matter.
Premium credit cards have stricter eligibility requirements. A strong credit profile can help in getting approval for such cards.
A good credit score of 800 will give you a better position to compare various borrowing offers. It will allow you to compare personal loan interest rates, personal loan processing fees and other terms from various lenders rather than relying on a single option.
Here are some hacks that can help you achieve a CIBIL score of 800: –
Timely payments are the most important factor determining your credit score. Develop a habit of paying EMI or credit card bills before the due date. Regular repayments will help in improving your credit score.
You should not fully utilize your credit limit as it can have a negative impact on your credit score. It’s advisable to keep the credit utilization ratio below 30% of your available credit limit and ideally below 20%. Keeping the credit utilization ratio low can help in improving the credit score.
Don’t make the mistake of paying the minimum amount due on your credit card. This will lead to late payment charges and high interest. Interest will be charged on the remaining balance as well as on new purchases. Hence, you should always pay your credit card bill in full every month.
Each application for your loan and credit card leads to a hard inquiry. If there are too many inquiries in a short span, then it can lower your credit score. Hence, it’s advisable to research a bit and check the eligibility of the lender before applying for a new loan or credit card.
To achieve a credit score of 800, you should have a mix of secured and unsecured credit in your portfolio. This makes lenders believe that you can handle different types of loans.
The length of your credit card also impacts your credit score. An older credit card indicates that you are financially stable and improves lender confidence. Keeping old cards active can strengthen your credit profile over time.
A higher credit card limit will reduce your utilisation ratio. This will improve your credit score and bring you near an 800 score.
Have a habit to check your CIBIL score at least once or twice a year. Many times, your CIBIL score is affected not because of your mistake but due to an error in the CIBIL report. Some of the common errors include a loan closed but the account still active, incorrect outstanding balance, incorrect personal or account details, etc. Getting such errors rectified will improve your CIBIL score.
When a lender checks your credit report as part of a loan or credit-card application, it is called a hard inquiry. Multiple such enquiries over a short period of time can affect your score.
Frequent use of a credit card can improve your CIBIL score, but only if you make timely bill payments and that too in full and not the minimum due amount. You can use a credit card for travel, fuel, dining, and online shopping, but use it wisely and don’t delay repayments.
If you have any outstanding dues, you should clear it as soon as possible. A history of delayed payments can negatively impact your credit score.
Moreover, you should be very careful about the “settled” remark. A settled account means the lender has accepted less than the total amount due. CIBIL notes that the lender can view settled status negatively. Hence, if possible, repay the remaining amount and get the lender to update the account status as closed.
There is no fixed timeframe in which you will hit an 800 score. Credit score improvement depends on your individual profile. You can take the above-mentioned actions, but it can still take time to update.
Here are some common reasons for your CIBIL score being stuck at 750: –
There are no fixed days under which your CIBIL score will improve from 750 to 800. If the reason for a lower score is high utilisation, then reducing outstanding balances can be reflected after the lender reports updated information. If your profile has older late payments or other negative information, then improvement can take a reasonable longer time.
1. One of the most common myths is that if you check your CIBIL score, then it will reduce. Actually, this is not true. When you check your own score, it is considered a soft inquiry, and it doesn’t have any negative impact on your credit score.
2. Another popular myth is that if you have a high income, then your credit score is going to be high. This is not true. Your salary, savings, investments and demat holdings don’t determine your CIBIL score. The score is based on your credit-related information.
3. It is also a popular myth that CIBIL itself is taken into consideration to approve or reject a loan. The lender makes the lending decision using the CIBIL score along with other information.
Yes, your CIBIL score can improve in a short span if the lender reports new information to the credit bureau. But there is no guarantee that your CIBIL score will improve from 750 to 800 in 30 days.
If high utilization is the main issue, then reducing balances could help once the updated information reaches the credit bureau. But if your profile has older repayment issues, multiple enquiries, or other negative information, then improving the score can take time.
A CIBIL score is an important factor determining your loan approval. People generally believe it’s enough to have a CIBIL score of 750 and don’t aim for higher. But a higher CIBIL score of 800 can give a lot of extra benefits like faster approval, lower interest rates, pre-approved credit card offers, better loan terms, etc.
People remain confused about how to increase CIBIL score from 750 to 800. But it’s not so hard. You just have to be consistent in your credit discipline. Pay EMIs on time, keep utilisation ratio low, avoid multiple loans, etc. However, the score won’t reach 800 suddenly, even after your decent credit behaviour. It can take a reasonable time to reflect. Till that, you need to be patient.
One can increase CIBIL score from 750 to 800 by making regular payments, keeping credit utilisation low, not applying for multiple loans, not closing old credit cards, etc.
There is no fixed timeframe after which your CIBIL score will reach 800. It depends on various factors like utilisation ratio, repayment history, credit age and inquiries. Some improvements will reflect after updated information is reported. Whereas rebuilding from past negative events can take longer time.
An 800 CIBIL score makes your personal loan application very strong. But loan approval doesn’t solely depend on your CIBIL score. Lenders also take into consideration other parameters like income, employment, existing debt, etc., to evaluate your loan application.
A score of 800 will make your personal loan application strong, but it doesn’t provide any guarantee for approval of an instant personal loan. The lender can also verify your income, existing liabilities, employment and various other factors before approving the loan.
There is no fastest way to improve a CIBIL score. You just have to follow the steps needed to improve your score. And the score will improve gradually with time.
No, checking your own CIBIL doesn’t reduce your score. It is considered a soft inquiry, which has no negative impact on your credit score.
Download our personal loan app to apply for a personal loan. Get up to 2Lakhs* as a personal loan. Download Now!


Sign into avail a personal loan up to ₹ 2,50,000
Unifinz Capital India Limited is a Non Banking Finance Company (NBFC) registered with the Reserve Bank of India (RBI). lendingplate is the brand name under which the company conducts its lending operations and specialises in meeting customer’s instant financial needs.
 RBI CMS
 RBI Sachet


