Did You Know?
We serve loans, the best way you can borrow
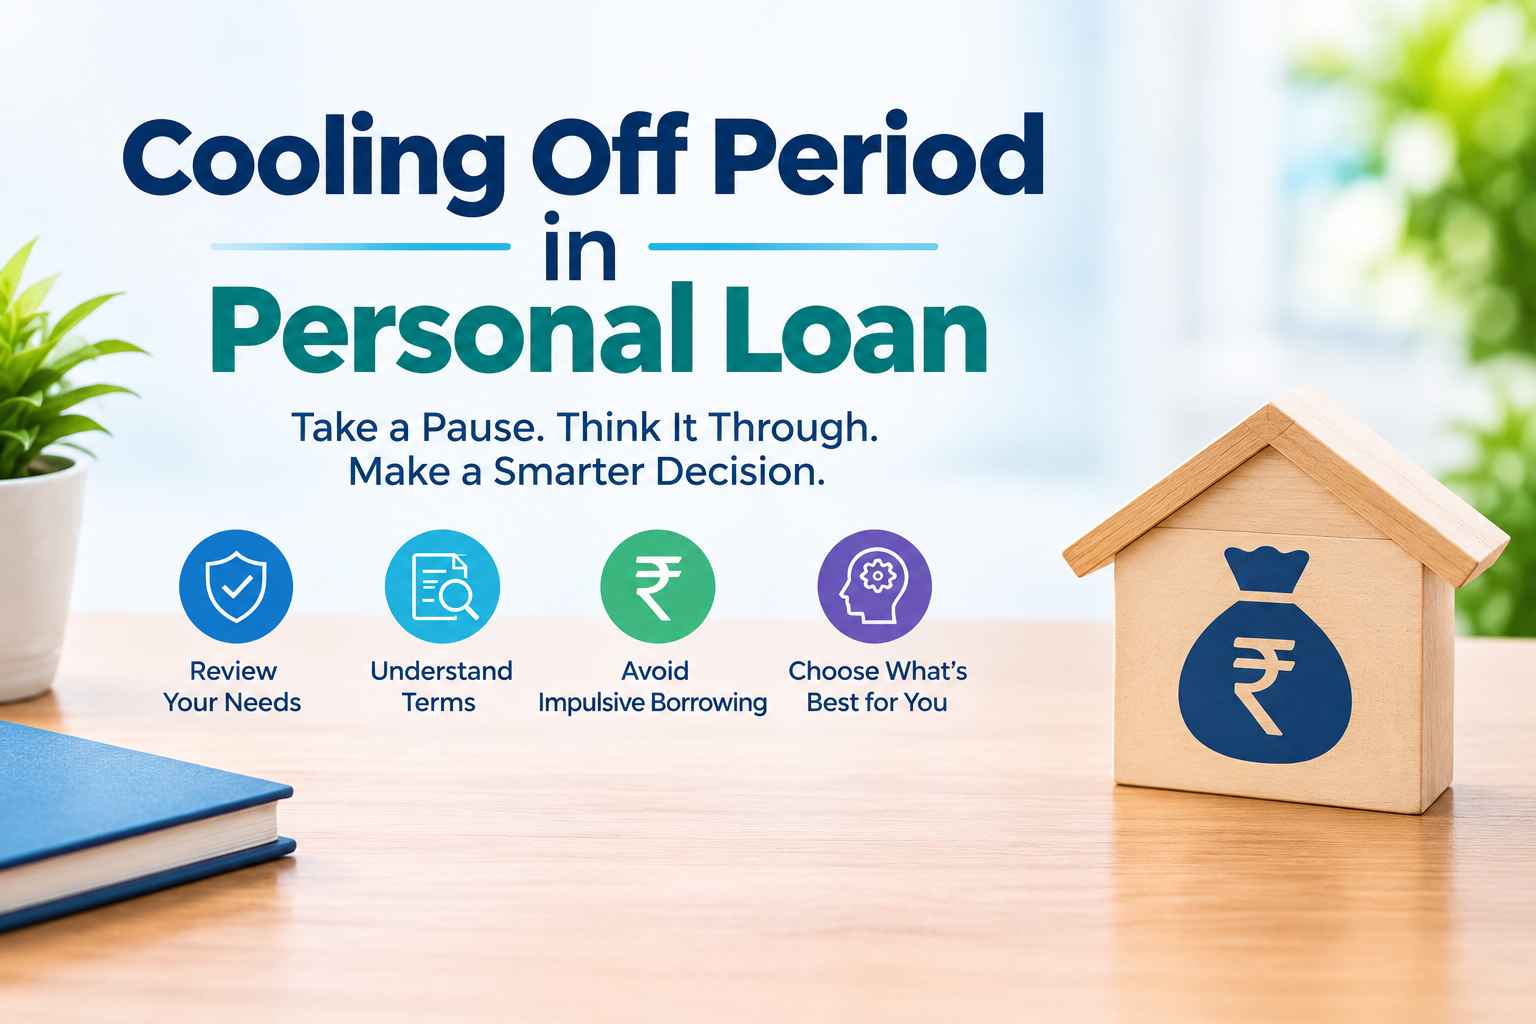

People take a personal loan for various reasons like marriage, vacation, home renovation, medical emergency, car repair, etc. Sometimes, you take this decision quickly and later want to cancel the loan. This is possible in the cooling-off period.
This is a short window given to you by the lender under which you can cancel the loan, and you won’t have to pay any penalty charges. In this blog, we will study in detail the cooling-off period in a personal loan, its meaning, importance and process.
The cooling-off period in a personal loan is a dedicated timeframe given to borrowers under which they have the right to cancel the loan without paying any penalty or having any negative consequences. This provides consumers a safety net. The cooling-off period can range from 48 hours to 7-14 days. During this period, if you cancel the loan, then the agreement is nullified. You can refund the full loan amount to the lender, and you won’t be charged any penalties.
The cooling-off period is quite important as it provides a kind of safety net to the borrowers after the loan has been sanctioned. Personal loans are generally taken for emergency or sudden needs. There are chances that an individual has taken the loan in a hurry and later on may want to change the financial decision he/she made. The cooling-off period gives that opportunity to rethink and take the final decision.
Here are some of the major benefits of the cooling-off period –
The loan cancellation process is as explained below –
First of all, you must read the agreement carefully to understand the cancellation terms. This means you shall check the length of the cooling-off period and any other requirements or procedures.
Contact the lender through email, customer care, or the lender’s mobile app and inform them that you want to cancel the loan during the cooling-off period. Ask them to initiate the loan cancellation process without penalty.
Submit the documents required for cancellation, like ID proof and reference number.
You have to repay the entire loan amount disbursed by the lender. Make sure that you follow the lender’s instructions for return of money.
Get written confirmation about the cancellation from the lender.
The RBI cooling period is a part of broader digital lending loan guidelines in India. This has been introduced to improve customer protection and encourage transparent and ethical lending practices.
Some of the critical guidelines are as under –
Borrowers shall be given a clear option to exit from a digital loan during the cooling-off period by repayment of principal and proportionate APR without any penalty charges.
The duration of the cooling-off period is determined by the lender’s board, but it cannot be shorter than one day.
If a borrower has decided to continue with the loan even after the cooling-off window closes, then they can also make prepayments under existing RBI rules.
Lenders can charge a one-time processing fee if the borrower cancels the loan in the cooling-off period, but the fee has to be disclosed in the Key Fact Statement (KFS).
If you cancel the loan during the cooling-off period, then its impact on your credit score will be minimal. Because the loan is not active yet, as lenders haven’t yet reported it to the credit bureau. Hence, cancelling within the cooling-off period doesn’t have any negative impact on your credit score.
Reasons why a cancelled loan doesn’t have any effect on your credit score:
A cooling-off period is not automatically available for all types of loans. Its applicability depends on the lender, loan product and applicable RBI regulations. For certain digital loans, borrowers get a cooling-off period during which they can exit the loan by paying the principal and proportionate annualised interest without being charged a penalty for prepayment. However, specific terms and conditions can vary between lenders and loan products.
Therefore, before you accept a loan, borrowers should check the loan agreement and Key Fact Statement (KFS) for details about the cooling-off period, applicable charges, and exit conditions. Understanding the terms can help borrowers make an informed borrowing decision.
The cooling-off period is an important aspect of personal loans, which gives borrowers a safety net. It allows borrowers to review the loan terms, and if not happy with that they have the right to cancel the loan. Moreover, there are no extra charges for loan cancellation if done during the cooling-off period. Before taking a personal loan, you should check the cooling-off period offered by the lender. This will help you decide how much time you have to review the loan and cancel if the need arises.
Yes, many loans offer a cooling-off period, especially digital loans and personal loans. In this period, the borrower can cancel the loan, and they won’t be charged any penalty.
As per RBI, the cooling-off period is a mandatory, borrower-friendly window which is determined by the lender but cannot be less than 1 day. In this period, the borrower can cancel the loan without paying any penalty.
As per RBI guidelines, the minimum cooling-off period for a digital loan is one day. The lender can provide a longer tenure as per the policy terms.
Yes, you can cancel the loan after accepting it if it’s in the cooling period. This period generally ranges from 48 hours to 7-14 days, during which, if you cancel the loan, you won’t be charged any penalty.
Yes, NBFCs do offer a cooling-off period option, especially for digital loans, as mandated by the RBI guidelines. The period is determined by the NBFC, but it cannot be less than one day.
Download our personal loan app to apply for a personal loan. Get up to 2Lakhs* as a personal loan. Download Now!


Sign into avail a personal loan up to ₹ 2,50,000
Unifinz Capital India Limited is a Non Banking Finance Company (NBFC) registered with the Reserve Bank of India (RBI). lendingplate is the brand name under which the company conducts its lending operations and specialises in meeting customer’s instant financial needs.
 RBI CMS
 RBI Sachet


